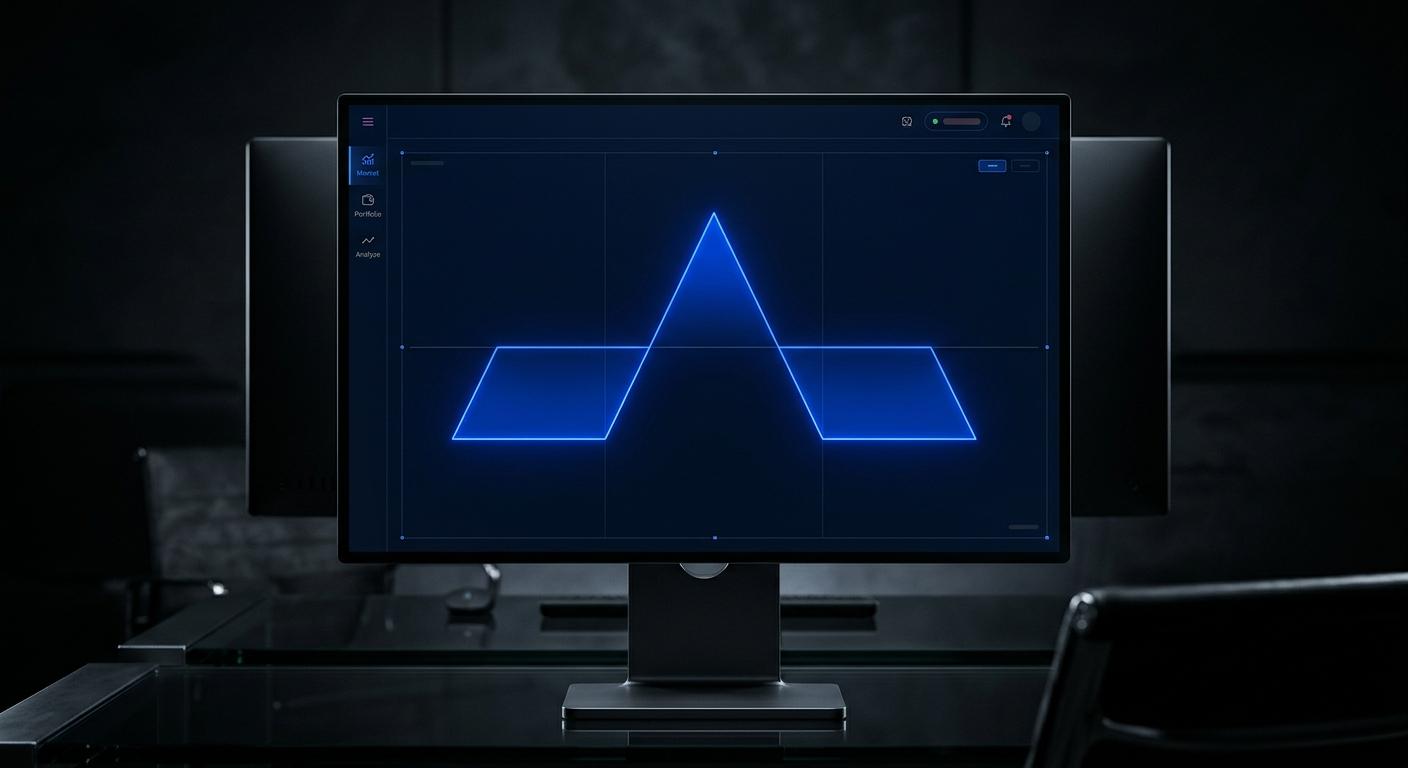
A stock keeps stalling at the same price, implied volatility is elevated, and you want to get paid for it going nowhere. That's the setup an iron butterfly is built for. You sell an at-the-money call and an at-the-money put, then buy a cheaper call above and a cheaper put below so the damage is capped if the move shows up anyway. The trade collects the largest credit of any four-leg neutral position, and in exchange it gives you the narrowest zone where you actually win. This guide walks through how the iron fly is built, the payoff math, how to pick strikes and expiration, and where it fits among the neutral options strategies traders use when they expect price to sit still.
What an iron butterfly is
An iron butterfly is four options on the same underlying, in the same expiration, with equal distance between the center strike and each wing:
- Sell one call at the center strike
- Sell one put at the same center strike
- Buy one call at a higher strike
- Buy one put at a lower strike
The two short options at the center are a short straddle. The two long options are insurance. Another way to read it: an iron butterfly is a call credit spread and a put credit spread stacked on the same short strike, which is why the credit is so much larger than a single bull put spread at the same width.
Because the short call and short put sit at the same strike, only one of them can finish in the money. That's the structural quirk that makes the iron fly different from every other condor-style trade: the body is a single point, not a range.
The payoff math
Three numbers define the trade, and all three come from the credit you collect and the width of the wings.
- Maximum profit = the net credit, earned only if the stock closes exactly at the center strike
- Maximum loss = wing width − net credit
- Breakevens = center strike ± net credit
The Options Industry Council's short iron butterfly page lays out the same structure, with the maximum gain at the body and the loss capped at the difference between the body and either wing less the premium received.
A worked example
AMD is trading at $160 ahead of a quiet stretch on the calendar, and you sell the 30-day iron butterfly:
Leg | Strike | Action |
|---|---|---|
Call | 170 | Buy |
Call | 160 | Sell |
Put | 160 | Sell |
Put | 150 | Buy |
Say the package comes in at a $6.00 net credit, or $600 on one butterfly. The wings are 10 points wide, so the most you can lose is $10.00 − $6.00 = $4.00, or $400. Breakevens are $154 and $166. Anywhere between those two prices at expiration, the position is profitable; outside them, it loses, up to the $400 cap.
Notice the shape of that risk: you're risking $400 to make up to $600, but the full $600 requires a pin at $160 to the penny. Realistically you're collecting a fraction of the credit, which is why most iron flies are closed long before expiration rather than held to the end.
Short iron butterfly vs long iron butterfly
The version described above is the short iron butterfly, and it's what traders mean when they say "iron fly." It's a credit trade that wants the stock to sit still.
The long iron butterfly flips every leg: buy the center call and put, sell the wings. Now you've paid a debit, you need a move past one of the wings, and your upside is capped by the long strangle you sold against it. It behaves like a cheaper, capped version of a long straddle, and it rarely gets used, because traders who want a breakout usually just buy the straddle or a wide strangle instead.
How the position behaves day to day
An iron butterfly is short volatility and long time decay, with gamma that sharpens as expiration approaches.
Theta works for you. The at-the-money options you sold decay faster than the out-of-the-money wings you bought, so a flat tape quietly adds value to the position every day.
Vega works against you. A spike in implied volatility inflates the short straddle at the center more than it inflates the wings, so the butterfly loses on an IV jump even if the stock hasn't moved. Entering when implied volatility is already rich, rather than chasing a trade into an earnings run-up, is most of the edge here.
Gamma is the one that bites. In the final days, a short at-the-money straddle flips from comfortably profitable to near max loss on a move of a couple of percent. That's the same force that makes 0DTE options so violent to be short, and it's why iron flies are often opened with two to six weeks left and taken off with a week or more to spare.
Picking strikes and expiration
The center strike is the whole trade. Put it where you genuinely expect the stock to settle, which usually means at the money, but not always. If your read on the chart says a name grinds back toward a volume shelf, you can shift the body there and sell a slightly skewed butterfly that leans bullish or bearish.
Wing width sets the risk-to-credit tradeoff. Narrow wings cut the maximum loss but also cut the credit and leave almost no cushion between the breakevens; wide wings collect more and give a bigger profit zone, but tie up more buying power. A common compromise is wings roughly one expected move wide, so the breakevens land near the edges of where the options market thinks the stock can travel.
On expiration, pick something long enough to survive noise. A 30-to-45-day iron butterfly gives you time to be wrong for a few sessions and still recover; a weekly iron fly on a high-beta name like COIN is closer to a coin flip on the next two closes. Expirations and strike spacing differ by product, and anyone learning the mechanics of options will get more out of a liquid underlying with penny-wide strikes than an illiquid one where the four-leg fill eats half the credit.
Iron butterfly vs iron condor
These two get compared constantly because they're built from the same parts. The difference is the body.
Iron butterfly | Iron condor | |
|---|---|---|
Short strikes | Same strike, at the money | Two different out-of-the-money strikes |
Credit collected | Larger | Smaller |
Profit zone | Narrow (a point, widened by the credit) | Wide (the whole range between short strikes) |
Win rate | Lower | Higher |
Risk per trade | Lower (credit offsets more of the width) | Higher relative to credit |
If you expect a stock to pin near a specific price, the iron fly pays better. If you only expect it to stay inside a range, the iron condor is the more forgiving structure, because its profit zone is a band rather than a point.
Both belong to the same family of defined-risk, neutral trades, and picking between them comes down to how precise your read is rather than which structure is better. That same trade-off between credit size and win rate runs through most of the short-premium options strategies a neutral trader ends up using.
A short strangle is the undefined-risk cousin of both. It collects a similar credit to the condor without buying wings, which means an unlimited tail; the comparison between a short strangle and an iron fly comes down to whether you're willing to pay for protection you'll usually never need.
Managing an iron butterfly
Decide your exit before the fill. Common approaches:
- Take profit at 25–50% of the credit. The last portion of the credit takes the longest to earn and carries the worst gamma risk.
- Cut at a multiple of the credit. Closing when the loss reaches 1x the credit received keeps a bad trade from becoming the full wing-width loss.
- Roll the untested side. If the stock drifts up, buying back the short put and reselling it closer to price collects extra credit and widens your effective breakeven, at the cost of tighter risk on the other side.
- Close before expiration week. The pin-risk scenario, where the stock finishes right at the short strike and you don't know whether you're assigned, is avoidable by simply being flat.
Assignment is the other thing to watch. The short options are at the money, so early assignment on the short call around an ex-dividend date is a real possibility. Traders who already run a covered call know the feeling of having shares called away the day before a dividend, and the call side of an iron fly works exactly the same way.
The short put can be assigned any time it's in the money, and it behaves like any other cash-secured put when it is: you end up long shares at the center strike. Being handed stock inside a defined-risk position isn't a disaster, since the wings still cap you, but it changes your exposure, so the cleanest response is usually to close the shares and the remaining legs together.
Trading an iron butterfly at a prop firm
Four-leg credit structures need the right permissions. At Vanquish, the Advanced Options plan carries Level 4 permissions, which cover vertical spreads, butterflies, iron condors, straddles and strangles, so an iron fly is on the table there. The Basic Options and Rapid plans are long calls and puts only. One detail worth knowing before you plan an index trade: SPX, XSP and VIX are restricted to single-leg long calls and puts even on Advanced, so iron flies belong on equities and ETFs like QQQ instead.
Position sizing matters more on an evaluation than it does anywhere else. A defined-risk butterfly makes that easy to calculate, because you know the worst case to the dollar before you click, and that number is what the trailing loss limit will see if the trade goes against you.
FAQs
Is an iron butterfly bullish or bearish?
Neither, by default. It's a neutral trade that profits when the underlying stays near the center strike. You can give it a directional tilt by placing the body above or below the current price, which turns it into a bet that the stock drifts to a specific level.
What's the difference between an iron butterfly and a regular butterfly?
A regular butterfly uses all calls or all puts and is usually entered for a debit. An iron butterfly mixes both, using a put spread below and a call spread above, and is entered for a credit. The payoff shapes are nearly identical; the iron version tends to have better liquidity because it uses out-of-the-money options on both sides.
How much can you lose on an iron butterfly?
The wing width minus the credit received, per butterfly, times 100. In the AMD example, $10 wide minus $6.00 credit equals $400 per contract, and nothing the stock does can make it worse than that.
When is the best time to open an iron fly?
When implied volatility is elevated relative to its own recent range and you expect the underlying to settle rather than trend. Rich option prices mean a larger credit, which pushes the breakevens further apart and gives the trade more room.
Do you have to hold an iron butterfly to expiration?
No, and usually you shouldn't. The maximum profit requires a close exactly at the center strike, which almost never happens. Buying the position back once a meaningful portion of the credit has decayed takes the gamma risk off the table.
Used well, the iron butterfly is a precision instrument: a high-credit, defined-risk way to express the view that a stock has stopped going anywhere. Used carelessly, it's a short straddle with a seatbelt, and the seatbelt gets tested more often than new traders expect. Size it by its maximum loss, enter when volatility is paying you, and take profits early. If you'd rather practice four-leg structures with a defined risk ceiling and a published rule set, the Advanced Options plan on the Vanquish plans page is where that strategy set lives.