You think MSFT finishes the next two weeks right around $420, and you want to get paid for being right about the number rather than the direction. A butterfly spread is the structure built for exactly that view: three strikes, four contracts, a profit peak sitting over your target price, and a cost that's often a fraction of what a single directional contract would run. The trade-off is that you need the stock to cooperate fairly precisely, and that's where the broken wing version comes in — it loosens the symmetry in exchange for taking on risk on one side.
Butterflies sit toward the advanced end of options trading because they combine long and short contracts in one position, which means an account has to allow selling contracts to open before one can be placed. They're also the clearest example of a payoff shaped around a specific price rather than a direction, which is why the structure rewards a forecast most traders never bother to make.
What a butterfly spread is
A butterfly is three strikes in one position, with the middle strike traded twice:
- Buy one contract at a lower strike (the lower wing)
- Sell two contracts at a middle strike (the body)
- Buy one contract at a higher strike (the upper wing)
All four contracts share the same expiration and the same underlying. In a standard butterfly, the wings are equidistant from the body — 10 points below and 10 points above, for example. The position is a debit: you pay to open it, and that debit is your maximum loss.
The payoff looks like a tent. At expiration, the position is worth the most when the underlying closes exactly at the body strike, because the long wing is deep in the money while both short contracts expire worthless. Move far enough in either direction and all four contracts offset each other, leaving you with nothing but the premium you spent. The Options Industry Council describes the structure the same way in its long call butterfly breakdown, noting that maximum profit occurs with the stock at the body at expiration.
Long call butterfly, with real numbers
Say MSFT trades at $418 and you expect it to drift toward $420 and stall there into expiration in two weeks. A long call butterfly built around $420:
- Buy 1 MSFT $410 call
- Sell 2 MSFT $420 calls
- Buy 1 MSFT $430 call
Assume the whole package costs $2.50, or $250 for one butterfly. Compared with a long call, which needs both direction and magnitude to work, you're funding most of the position with the two contracts you sold.
Price at expiration | Outcome |
|---|---|
$410 or below | All calls expire worthless; lose the $250 debit |
$412.50 | Lower breakeven |
$420 | Maximum profit: $1,000 wing value − $250 debit = $750 |
$427.50 | Upper breakeven |
$430 or above | Wings offset the body; lose the $250 debit |
Three numbers define the trade. Maximum loss is the debit, $250. Maximum profit is the wing width minus the debit, $10.00 − $2.50 = $7.50, or $750. Breakevens sit one debit's distance either side of the body, at $412.50 and $427.50.
That roughly 3:1 payoff is the appeal. The catch is the width of the profit zone: MSFT has to land inside a $15 window, and the full $750 only arrives with the stock pinned at $420 on the last day. Before expiration, a butterfly that's working might show a third of its potential value, because the two short contracts in the body still carry time premium.
Long put butterfly
The put version is a mirror image, and it produces the same payoff tent: buy one higher-strike put, sell two at the middle strike, buy one at a lower strike. Using QQQ with a target of $480, you'd buy the $490 put, sell two $480 puts and buy the $470 put.
Traders pick the call or put version based on which side has better pricing and tighter markets, not because one is bullish and the other bearish. A butterfly's bias comes from where you place the body relative to the current price, not from whether you build it out of calls or puts — one of the places where the usual logic of calls versus puts stops applying cleanly.
The broken wing butterfly
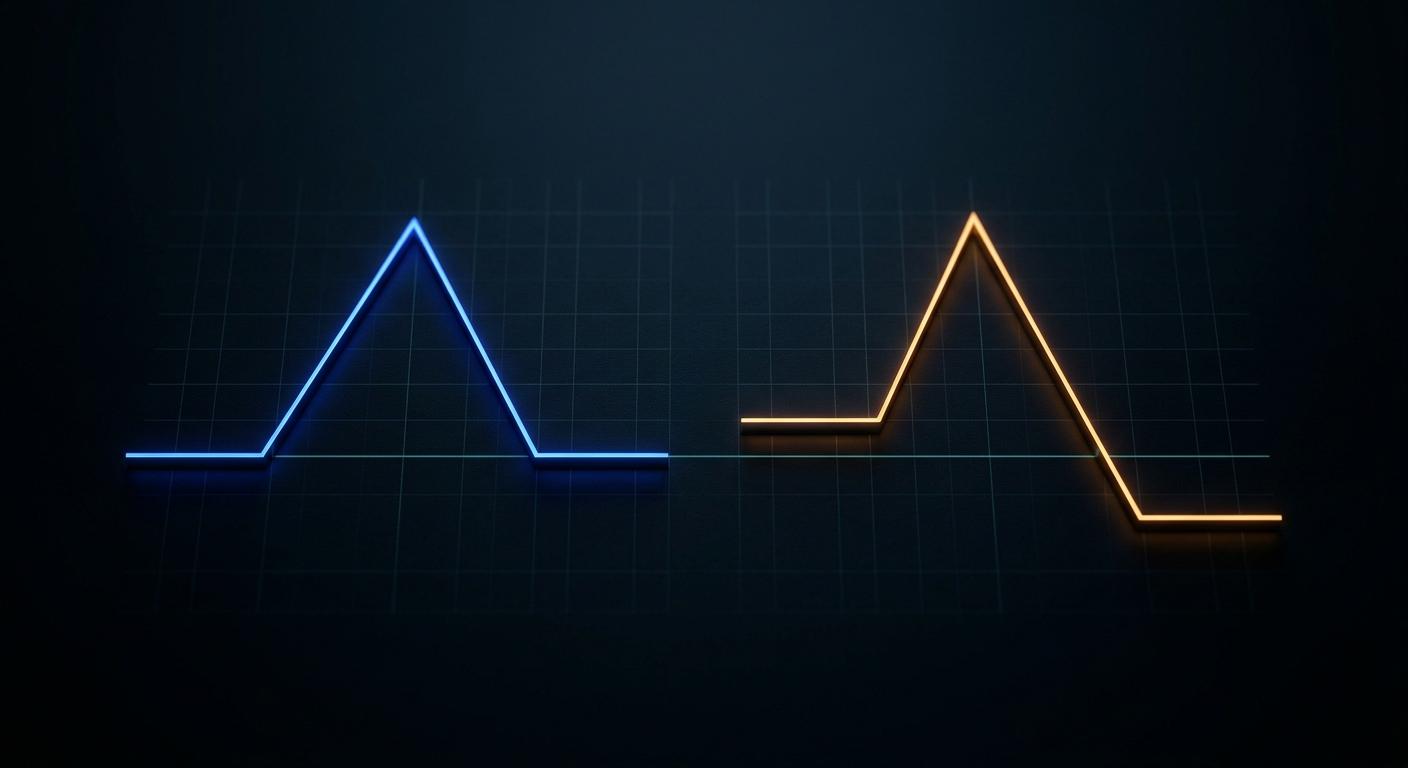
A broken wing butterfly, sometimes called a skip-strike butterfly, keeps the same three-strike shape but widens one wing. Take the MSFT trade and move the upper wing out:
- Buy 1 MSFT $410 call
- Sell 2 MSFT $420 calls
- Buy 1 MSFT $435 call
The $435 call is cheaper than the $430 call, so the package costs less — often it opens for a small credit. Say you collect $1.00, or $100.
That changes the risk profile in a specific way. Below $410, every contract expires worthless and you keep the $100 credit: the downside is now a small win rather than a loss. At $420 you still get the full $1,000 of wing value plus the credit, so $1,100. But above $435, the mismatched wings leave you short $5.00 of intrinsic value — the 15-point wide wing minus the 10-point narrow wing — for a loss of $500 less the $100 credit, or $400.
In plain terms: you delete the risk on one side and concentrate it on the other. You'd place the broken wing on the side you consider less likely. A trader who thinks AMD is more likely to chop sideways or fade than to rip 12% higher might break the upside wing, accepting that a violent rally is the one scenario that hurts.
Two things to watch. The maximum loss on the wide side is larger than the credit received, so sizing by the credit alone understates the risk. And because the position carries directional exposure once the underlying moves toward the body, a broken wing butterfly behaves less like a neutral trade than its symmetric cousin as expiration approaches.
Choosing strikes and expiration
The body is the forecast. Put it where you expect the underlying to settle — at a round number that keeps attracting price, at a level where open interest is concentrated, at the top of a range a stock like COIN keeps failing to clear.
Wing width controls everything else. Narrow wings cost less and pay a higher multiple but shrink the profit window. Wider wings cost more, widen the window and lower the multiple. A $5-wide butterfly on a $120 stock is a precision instrument; a $20-wide butterfly on the same name is closer to a range trade.
Time matters as much as placement. Butterflies make their money from time decay in the body, and that decay accelerates in the final week. Open one 45 days out and it barely moves even when you're right, because the two short contracts still hold substantial premium. Open one with 5 to 10 days left and the position responds quickly — in both directions. Elevated implied volatility also compresses butterfly prices, since the market is paying up for the chance of a big move away from your body strike.
Managing the position
A few practical points that decide whether butterflies work in practice:
- Take profits early. Holding to expiration for the theoretical maximum means accepting that the underlying can walk away from your body in the last hour. Many traders close at 50% to 70% of maximum value.
- Mind the short contracts. The two contracts in the body carry the same assignment exposure as any short call or short put, and American-style equity options can be assigned at any time, particularly around ex-dividend dates.
- Avoid the pin. If the underlying sits right at the body into the close on expiration day, you can end up assigned on the shorts while the wings expire, leaving an unwanted stock position. Closing the whole structure beforehand removes the problem.
- Trade liquid names. Four legs mean four spreads to cross. On wide markets, the slippage can eat a meaningful share of the expected profit, which is why NVDA, SPY and index products are more common butterfly underlyings than thin single names.
- Enter as one order. Legging in piecemeal exposes you to naked short contracts if the market moves between fills.
Where butterflies sit among defined-risk trades
Compared with the defined-risk spread strategies traders use more often, a butterfly is the narrowest and cheapest of the group:
Strategy | Built from | Profits when | Typical cost |
|---|---|---|---|
Long butterfly | 4 calls or 4 puts | Price pins the body | Small debit |
Broken wing butterfly | 4 calls or 4 puts, one wide wing | Price pins the body or drifts to the safe side | Small debit or credit |
Iron butterfly | 2 calls and 2 puts | Price stays near the short strikes | Credit |
Iron condor | 2 calls and 2 puts, four strikes | Price stays inside a range | Credit |
The closest relative is the iron butterfly, which produces a near-identical payoff using both calls and puts and opens for a credit instead of a debit. The practical difference is usually pricing and margin treatment rather than strategy, so traders check both before choosing.
At Vanquish, the permission to sell contracts to open comes with the Advanced Options plan, which carries Level 4 permissions covering butterflies, condors, verticals, straddles and strangles. The Basic Options and Rapid plans are long calls and puts only, so a butterfly isn't available there — the same way a covered call needs permissions that a purely long-only account doesn't have. One restriction to note on Advanced Options: SPX, XSP and VIX are limited to buying single-leg calls and puts, so index butterflies would be built on products like SPY or QQQ instead.
FAQs
Is a butterfly spread bullish or bearish?
Neither by default. The bias comes from where you place the body relative to the current price. A body set above the market is a bullish butterfly; one set below it is bearish; one set at the money is a neutral bet on the underlying going nowhere.
What's the maximum loss on a broken wing butterfly?
The width of the wide wing minus the width of the narrow wing, minus any credit received. In a 410/420/435 call structure opened for $1.00, that's $15 − $10 = $5.00 of width, less the $1.00 credit, so $400 per butterfly above $435 at expiration.
Why is my butterfly barely worth more even though the stock hit my target?
Because the two short contracts in the body still hold time premium. A butterfly only converges on its maximum value in the final days before expiration, which is why entries three or four weeks out often look flat even when the forecast is correct.
Can you trade butterflies on 0DTE options?
Yes, and same-day butterflies are popular on index ETFs precisely because the payoff resolves within hours. They demand tight execution: with no time left, the structure swings hard as the underlying moves through the body, and fills matter more than usual.
How many butterflies should I trade at once?
Size by the debit, not the contract count. Four butterflies at a $250 debit is $1,000 at risk, which should be measured against your account the same way any single position would be. On broken wing versions, size by the worst-case loss on the wide side rather than the credit received.
A butterfly spread rewards a particular kind of thinking: not "this goes up" but "this ends near here." That makes it a precise tool and a demanding one, and the broken wing variant is the version most traders reach for once they accept that pinning a strike exactly is hard. Both belong in a rotation of options strategies rather than at the center of one — a handful of well-placed butterflies around earnings calm, range tops or expiration pins, not a daily habit.
Practicing structures like these under a published set of rules, with no daily loss limit and no time pressure, is what the Advanced Options plan is built for.